All posts

Summary
- 🗽We gave 160 young adults (ages 18–30) in the South Bronx and Harlem $12,000 over six months— including an $8,000 lump sum — one of the largest single cash infusions in a U.S. cash program to date.
- 🪙 We delivered payments in USDC (a digital dollar) through Coinbase, using its low-cost Base network to minimize transfer costs.
- 📈 Cash helped young people make improvements in financial wellbeing, increase savings, and reduce difficulties in paying rent.
- ❓Fewer young adults felt confident about their future and in control of their life decisions by the pilot’s end — a puzzling result we dig into below.
When 160 low-income young adults across the South Bronx and Harlem enrolled in our Future First New York (FFNY), the first U.S. crypto cash pilot, many asked us a fair question: “Is this a scam?”
New York daily life doesn’t wait, and neither does inflation. The New York metro area hit 4.1% annual inflation in this summer, above the 3.5% national rate. $12,000 in cash over six months, delivered in cryptocurrency no less, sounded too good to be true to a lot of recipients. Some associated all crypto with Bitcoin’s headline-grabbing unpredictability. Others had never touched it.
In running this pilot, Coinbase and GiveDirectly wanted to answer two questions:
- Does $12,000 help young adults build financial stability?
- Can we use blockchain to deliver aid to low-income young adults in the U.S. quickly and safely?
Here’s what we learned from 160 young New Yorkers about money, agency, and building a future.
$12,000 to young adults in one of the poorest parts of the U.S.
Our program ran in Harlem and the South Bronx, in and around New York’s 15th Congressional District. This area is consistently the poorest in the country with nearly a third of residents living below the U.S. poverty line, more than double the state and national rates. Recent gentrification is pushing up rents for local residents.
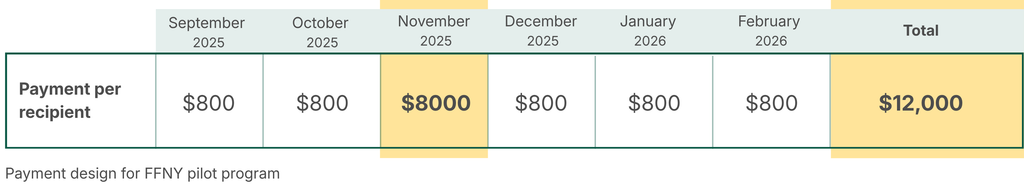
We sent $12,000 total over 6 months, including a one-time $8,000 lump sum, which is one of the largest single cash infusions in a U.S. cash program to date. Past GiveDirectly research in the U.S. and Africa finds most people prefer a large lump sum, and that it can have a better impact than spreading the same amount over small monthly payments.
We enrolled young adults ages 18 to 30 because they were likely to be able to utilize a large cash infusion for productive investments like education, new businesses, or a first apartment.
Rather than run a public application for this pilot, we enrolled 160 recipients through youth mentorship organizations that already had their trust. That let us skip the heavy verification and customer service machinery an open call would require, and these partners helped us build safeguards so everyone understood the benefits and risks of participating in the program.
Delivering payments via crypto was more efficient but initially unfamiliar to recipients.
For the first time, we tested delivering funds via USDC, a crypto stablecoin pegged 1:1 to the dollar, through Coinbase’s platform.
Many recipients started out skeptical about receiving payments in crypto — but that skepticism faded once they received their first payment and grew familiar with the platform. As one focus group participant told us: “I wasn’t into crypto before being selected, but now I know how to work Coinbase, and I have a Coinbase debit card.”
Step-by-step guides, transparent payment schedules, and responsive customer service helped build confidence quickly. By the end of the 6 month pilot:
- 100% of payments were delivered successfully — more than $2M in total transfers.
- Transaction fees were less than 1% of transfers using Base, Coinbase’s layer-2 blockchain, saving crucial overhead dollars.
- 89% of recipients felt safe receiving funds this way.
Recipients said digital wallets activated their ‘banker brain,’ encouraging saving and investing
Receiving funds in a separate crypto wallet meant that program money was automatically separated from daily spending accounts. For one focus group participant, this separation helped them practice their “banker brain”, a shift from immediate spending toward saving and investing.
“I feel like it was very convenient because you could store your money with the USDC and it’ll grow,” they told us. “You could take out however much you wanted, and it’ll keep growing.”
Recipients built savings and eased their rent stress with cash in hand
We ran a small mixed-methods evaluation — before and after surveys plus focus groups — to understand how cash helped young people. These results reflect a small, 160-person pilot, so we’re reading them as directional rather than conclusive.
Unconditional cash gave recipients room to move from everyday survival into future planning. “Coming from lack and limitation, you really just got to work with what you have,” said one focus group participant. In discussions with recipients, that showed up as:
- Immediate needs: paying back rent, clearing utility backlogs, groceries, keeping phones on.
- Career investment: funding small businesses (a perfume line, a social-mission restaurant) and trade certifications (esthetics, dermatology, business management).
- Family support: 39% used funds to help their family — covering a parent’s rent, a sibling’s tuition, or support sent abroad.
| Measure | Before | After | Change |
| Average savings | $320 | $1,488 | +$1,168 (+365%) |
| Share with more than $500 in savings | 8% | 33% | +25 pp |
| Difficulty paying rent | 67% | 27% | -40 pp |
| Often struggling with bills | 31% | 11% | -19 pp |
| Able to cover $400 emergency | 22% | 38% | +16 pp |
Cash surfaced new uncertainty, and recipients had ideas for how to navigate it
One finding surprised us: fewer recipients felt confident about their goals and future.
| Measure | Before | After | Change |
| Have goals for the future | 96% | 78% | -18 pp |
| Feel able to achieve goals | 94% | 79% | -15 pp |
| Feel in control of life decisions | 90% | 73% | -17 pp |
This is a puzzling result. It may reflect factors unrelated to the cash altogether, like growing housing costs, a worsening job market, or other new pressures. It’s also possible that receiving cash made recipients more aware of the limited agency they have to change their circumstances, even as their financial situation numerically improved. It may also be that our survey, coming just a few weeks after their last payment was sent, came at a unique moment when they were considering how to navigate their future without our payments. Untangling which of these is driving the shift would take further research.
Focus group conversations added some texture, without fully resolving the question. One participant, even after being fired, described “an overwhelming feeling of calmness” that let them focus on building rather than just surviving. Another put it this way: “being financially stable… that’s something that you can’t really control, especially living in New York, because it’s expensive out here… anything can happen.”
When we asked focus group participants what they’d want in future programs, they were clear: keep the cash unconditional, but offer optional access to:
- Financial advising: one-on-one coaching on credit building and homeownership.
- Tax & credit literacy: how cash, bank accounts, and credit scores interact.
- Crypto literacy: platform security and long-term investing.
Recipients were direct about scale, too: $12,000 over six months was a good start, but lasting independence in a high-cost city like New York likely takes more — $24,000+ over 12 to 24 months, by their estimate.
Rising costs are closing the door on upward mobility for young adults. Cash cracked it back open.
Policymakers are already experimenting with ways to help young people build a financial foundation, from baby bonds to new federal children’s savings accounts. Building on the directional evidence from FFNY, additional research could inform how the amount, duration, and structure of support may change a young person’s trajectory.
Does pairing cash with optional coaching — credit building, tax literacy, crypto education — outperform cash alone? Does a larger, longer transfer — recipients pointed to $24,000+ over 12 to 24 months — make these gains durable rather than temporary?
Our pilot showed that cash can help young adults build financial stability while meeting immediate needs and investing in their futures. The next question is whether and how it can change their long-term trajectory.